- AWS revenue rose 39.3%; trailing free cash flow was a $42.4bn outflow.
- Amazon retained its approximately $220bn 2026 cash capital-spending plan.
- The initial share decline was after hours; cash flow is not accounting profit.
Amazon delivered rapid cloud growth on October 29 and still received a cold reception. AP’s report, timestamped 20:27 UTC, described an after-hours decline of about 7%. That is a timestamped reaction, not a live quote or the regular-session closing change.1
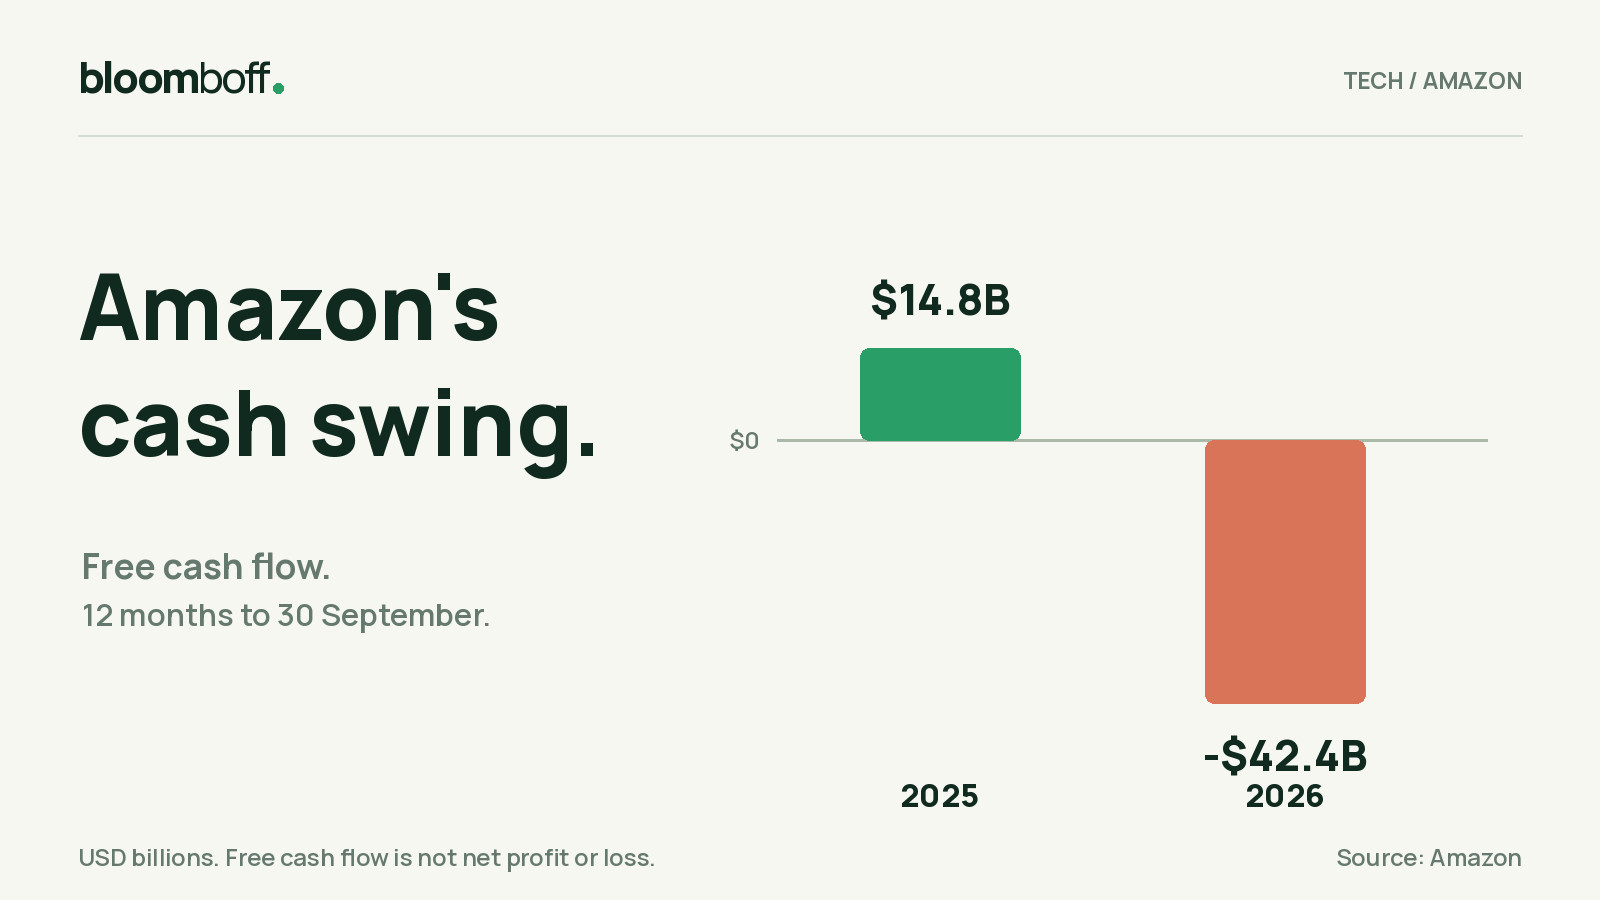
The tension is in Amazon’s own numbers. AWS quarterly revenue reached about $46 billion, up 39.3% from a year earlier. Meanwhile, free cash flow for the twelve months through September became a $42.4 billion outflow, versus a $14.8 billion inflow a year earlier.2
Amazon attributed the deterioration mainly to increased property and equipment purchases, primarily for AI. It retained an approximately $220 billion cash capital-spending plan for 2026.2
That does not mean Amazon lost $42.4 billion in accounting profit or ran out of cash. Free cash flow measures what remains after operating cash flow is reduced by the relevant equipment spending. Expanding infrastructure can consume cash even while the business generates profit.2
The question is whether today’s construction bill earns enough tomorrow. Strong cloud demand helps the case; it does not eliminate the cost or guarantee the future return.
Bloomboff’s take
The cloud is growing. So is the bill. Investors appear increasingly interested in the bit of the presentation where the money comes back.